| ← All communiqués |
|
||
|
30 March 2017
"Ring Around the Rosie" is just a silly nursery rhyme and we shouldn't pay too much attention to the words ... |
||
30 Mar 2017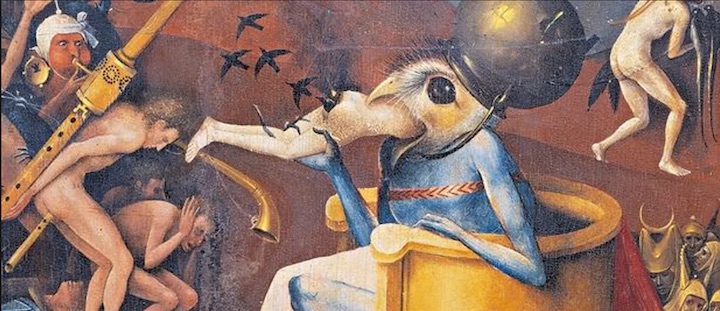
With the final verse of "we all fall down" referring to the inevitable death due to the disease. Conversely, it is also tempting for a person to assume that their default behaviour risk profile as an investment strategy is well thought out. On analysis in many instances suggests otherwise. As any good money manager will tell you, investment risk is not a one-way street. Even if you are successful as an investor, there are times when the markets will take some of your money. The real art is to ensure that these losses are manageable and that they fall within your overall investment strategy. This was clearly illustrated during the financial crisis of 2008/9 when financial institutions and private investors alike were devastated by losses during the market crash. By identifying meaningful goals and asking the right questions, can help prevent one from all falling down. Nobody likes making a loss, but allowing your risk aversion to determine your asset exposure is not always the best tactic. Instead, your investment risk profile should be a function of how long you have until you reach your goal. Any person attempting to beat inflation, is going to experience losses during an investment career. "If you are going to sell every time the stock goes down, you will never win, anymore than a general who always retreats when the enemy advances." - John Train Before making an investment, you should ask yourself five questions:
In an article written by Jeanette Marais, director of Allan Gray Investment Services and Allan Gray Unit Trust Management: Our investment goals depend on our personal priorities in life and there is no generic set of goals that applies to everyone, and no set timeline for achieving them. Even though certain goals may be similar in nature, we all have different timelines, risk profiles and personal circumstances, and our portfolios need to be constructed accordingly. Consider your time horizon Your time horizon has an important impact on your choice of savings vehicle and how much you need to contribute. Saving for short-term goals provides the foundation for financial security. Short-term goals can include putting money aside for an emergency fund to cover unexpected expenses and to act as a buffer for potential short-falls. Your medium- and longer-term objectives could vary, from saving for your child’s education or wedding, for example, to saving for your retirement. Since different types of investments behave differently over time, knowing how long you have to invest, and thinking about when you might need access to your money, can help you decide how much short-term volatility you can afford. It is important to put a plan in place and to pick the investments, or combination of investments, that are appropriate for each objective and time horizon. A longer time horizon usually means you can afford to take some risk with your money to achieve growth that contributes meaningfully towards your goals. If you are going to choose more risky investments, however, you need to be comfortable with market fluctuations. Returns do not come in a straight line. If you decide to draw money early from a long-term investment - either because you need it, or because you lose your nerve - you run the risk of locking in losses if the market is going through a down period. On the other hand, choosing to save in a bank account, or with a very stable investment product, presents you with another risk: inflation. Over time, inflation erodes the value of your money, leaving you able to buy less with the same amount of rands. Unfortunately, even if you save consistently, if the money you put away doesn’t grow enough to at least have the same amount of purchasing power at some point in the future, then you are not being rewarded for your discipline and sacrifice and you are in fact losing money. Risk versus volatility ‘Risk’ and ‘volatility’ are not the same thing. Think of risk as the potential of permanent loss of capital, whereas volatility is essentially the fluctuation in an investment’s value. Different types of investments carry different levels of fluctuation, and also deliver different returns. Asset classes with the potential for greater returns are associated with increased short- to medium-term volatility. Although the dips and troughs in value from a volatile investment should be on paper only, they result in permanent capital loss if you disinvest at the wrong time. You should avoid volatile asset classes if you know you will need to access your money in the short term. However, just because an investment is more volatile does not necessarily mean that it more risky in the long term. The real risk is permanent capital loss, not how smooth the ride is. Make conscious choices Understanding how much risk you are comfortable taking on, and how much return, ideally, you need to achieve, and investing accordingly, is key to allowing you to remain disciplined and committed to your investment plan. This can be difficult at times: between the fear of losing hard-earned cash and the fear of missing out on a great opportunity, it is understandable that many investors get distracted along the way and have the urge to chop and change their investments. If you make conscious choices based on your personal profile, it is easier to stay committed to your long-term plan. A financial adviser can help tailor your savings to suit your characteristics and objectives and ensure that you have a diversified portfolio that caters for both short-term and long-term goals. Our integrated wealthcare approach is based on your personal priorities and aspirations. This process is designed to give you a clear course of action for pursuing your goals that span various time horizons and life stages to empower you to do extraordinary things with your wealth, both now and in the future. I look forward to talking with you again soon. Regards, Shane Thom, CFP® GTP(SA)™ |
Editor: Shane Thom, Silke Financial Services FSP No. 12462 · An Authorised Financial Services Provider Copyright © 2017 by Silke Financial Services CC – All Rights Reserved. |