| ← All communiqués |
|
||
|
5 July 2015
Market Comment |
||
|
05 July 2015 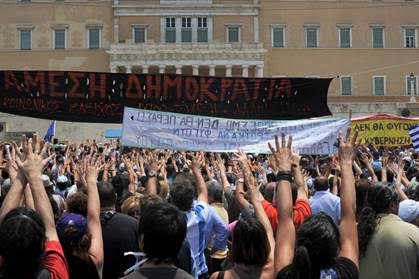
The economic update below are compiled by Kevin Lings, STANLIB's Chief Economist. To listen to the Monthly Economic Wrap click on this link: http://www.stanlib.com/EconomicFocus/Pages/EconomicFocus.aspx A week ago markets were happy because it looked like everyone wanted a deal on Greece. The probability of a Greek exit from the euro was put at 20%. Now that probability has shot up to as high as 80%, the highest it has ever been, through all the Greek troubles of the last four or five years. So markets are a tad shocked. This was not expected. So now the big question is what effect it will have on the rest of Europe's markets and the global markets... beyond today and perhaps most of this week. No-one knows for sure, but Greece's economy has shrunk by some 30% since 2007. It is now 1.8% of the Eurozone GDP. The population is around eleven million people, similar to Zimbabwe (similar economies?). So it really is a small economy and obviously an exit from the euro will cause enormous short-to-medium-term pain for Greeks; but for the rest of Europe it shouldn't amount to much is our best guess, beyond a day or two of ructions. The Dow Jones Euro Stoxx 50 Index is trading where it was ten days ago, down -3.9% today, up about 12% so far in 2015 in euros. US futures are -1.3%. It is said that the risk of potential contagion if Greece leaves the euro is roiling global markets, with the euro currency also down to a three-week low against the dollar of $1.106. Contagion refers to other countries that are struggling, such as Portugal, perhaps looking to follow Greece's example. However, how realistic is this? The JSE All Share Index is down -1.3% in fairly early trading at 52,011, back where it was 10 days ago - and last July 2014. Financial & Industrials are -1.4%, while mining shares are -0.3%. Naspers is down more than most at -4.3% after Tencent fell a similar percentage this morning in Hong Kong. Our Banks Index is -1.1% One positive this morning, totally overlooked because of Greece, is that China cut interest rates by 0.25% with effect from today, their 4th cut in the last 8 months, in line with the government's intent to prop up growth. This was after the Shanghai Composite Index fell over 20% from its recent high, amidst record high margin debt (money borrowed to buy shares), aggravated also by a large number of new or initial public offerings (new share listings). Our SA government bond yields have spiked up a bit amidst some selling out of riskier emerging markets (risk-off), which in turn is hurting listed property. This in spite of a risk-off move offshore out of equities into bonds. The bond yield of the German 10-year has fallen sharply from 0.91% on Friday to 0.73% today (flight to safer investments). When bond yields decline, prices/values rise. Similarly the US 10-year yield is down from 2.47% on Friday to 2.33% today. This yield has broadly been rising from 1.66% at end January to 2.5% recently, in response to a lower risk of deflation and higher economic growth/employment and better wage growth too. As yet, the rise in yields has not upset the longer term bull market (lower yields/higher prices). Meanwhile the global listed property index is back at its low for the year, down -10.5% in dollars, partly because of the higher bond yields. The forward dividend yield is now a fairly juicy 4%, at least juicy for developed markets, where cash continues to yield 0% and bond yields are under 2%.The chart in our main report shows that the fund is back at similar levels to May 2013, in dollar terms. STANLIB's view is that IF the US 10-year yield rises from the current 2.33% to 4.25% in a year's time, then Global Listed Property should return about 6.25% in dollars in that 12-month period. Should bond yields remain lower though, returns could be closer to 10%+ (See below; BCA expects yields to be lower). Local listed property had started to recover a bit after its recent -11.5% correction, but today it is down more today and still looks quite expensive on a dividend yield of 5.6%, which is just 67% of the current SA 10-year bond yield of 8.3%, compared with the long-term average of 90%. However, one of the Stockbroker analysts, Naeem Tilly of Avior, thinks that currently the SA Listed Property Index is trading at fair value relative to bonds, once you dig down a bit deeper. For example, the SA-only listed property shares, being those that have no offshore exposure, are trading on a forward dividend yield one year out of 7.5%, which is 90% of the current bond yield of 8.3%. These shares comprise 76% of the index, he says. Those shares with offshore exposure are currently trading at a big premium to the local shares, meaning their forward dividends yields are much lower, ranging from 3.9% for those invested in Rumania to 5.5% for those in Australia. Obviously there is still some risk that bond yields may rise further once US interest rates are hiked; for example consensus expects the US 10-year to rise to 2.8% from the current 2.3% at that stage. If consensus is wrong and the US yield rises much less, that would be positive. Although STANLIB has taken care to ensure that the content on this website is true and accurate, STANLIB cannot be held responsible for any inaccuracies in the information herein. The information and content (collectively ‘information') provided herein are provided by STANLIB as general information. STANLIB does not guarantee the suitability or potential value of any information or particular investment source. Any information herein is not intended nor does it constitute financial, tax, legal, investment, or other advice. Before making any decision or taking any action regarding your finances, you should consult a qualified Financial Adviser. |
Editor: Shane Thom, Silke Financial Services FSP No. 12462 · An Authorised Financial Services Provider Copyright © 2015 by Silke Financial Services CC – All Rights Reserved. |