| ← All communiqués |
|
||
|
25 September 2009
The Rand - Is The Trend Your Friend? |
||
|
The article below was recently published by Alphen Asset Management. Silke Financial Services deems it appropriate to quote. Accurately forecasting short term movements in stock markets is a particularly difficult task at the best of times. Unsurprisingly it is even trickier when it comes to currency market predictions. We will therefore not attempt to make these today. The events that unfolded in the second half of 2008 created the perfect storm for emerging market currencies such as the South African Rand. As we argued in an Alphen Angle in October 2008, the combination of SA's large current account deficit, slowing global economic growth, an unwinding of the emerging markets risk trade, falling commodity prices and a relatively uncertain domestic political environment were some of the factors that contributed to the move from R7.20 to R11.85 vs the US Dollar in a mere 10 weeks up to October 2008. Of the abovementioned factors most seem to have since reversed and, this coupled with past and anticipated foreign inflows, can be cited as being the driving force behind our beloved rand's comeback, which has seen it trading as low as R7.27 in recent weeks. When making investment decisions it is all too easy to let current sentiment and short term noise factors get the better of one. We argue it is important to sometimes take a step backwards and view developments over the longer term. One particularly interesting development we have been watching is the pattern that has emerged in the Rand/US Dollar exchange rate over the past 25 years (see chart). 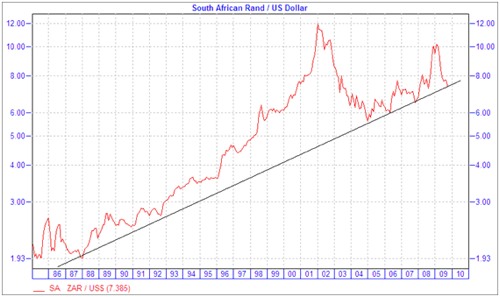
Source: I-Net Bridge, Alphen Asset Management The local unit has depreciated by an annual rate of 5.8%, largely in line with its inflation differential. After the rally since late last year the rand finds itself at an interesting juncture, right on its supporting trend line that has formed over the last two-and-a-half decades. While the stars driving current rand strength are aligned there is a good chance most positives have been incorporated into the price. We continue to strongly advocate allocating a portion of one's portfolio offshore. Silke Financial Services will not be liable for any loss or damage suffered by any party as a result of their acting on or failing to act on this information. The views of the contributors may not necessarily reflect the house view of Silke Financial Services. Views and opinions expressed herein may change with market conditions and should not be used in isolation. It is strongly recommended that you contact a financial planning professional prior to making any investment decisions. Silke Financial Services are skilled risk and investment strategy consultants that provide a unique service offering not available elsewhere in the marketplace. |



Editor: Shane Thom, Silke Financial Services FSP No. 12462 · An Authorised Financial Services Provider Copyright © 2009 by Silke Financial Services CC – All Rights Reserved. |
